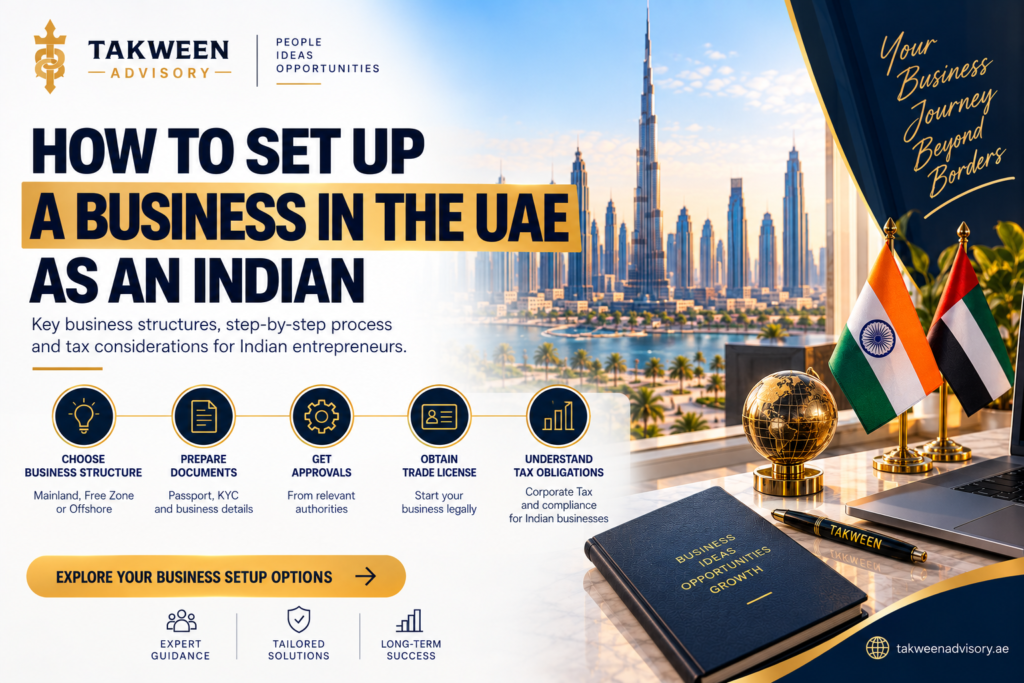
The UAE has become an attractive destination for Indian entrepreneurs who want to expand internationally, reach new customers, and build a business in a well-connected global market. From IT services and consultancy to trading, e-commerce, and manufacturing, the country offers several options for establishing a company.
However, before you setup business in uae, it is important to understand which business structure suits your activities, how company registration works, and what taxes may apply in both the UAE and India. Choosing the right structure at the beginning can help you manage costs, meet legal requirements, and avoid unnecessary tax complications later.
This guide explains the main company formation options, the registration process, UAE tax rules, and important considerations for Indian citizens planning to start a business in the UAE.
Why Do Indian Entrepreneurs Choose the UAE?
The UAE offers access to customers across the Middle East and opportunities to serve international markets. Its business environment attracts entrepreneurs working in technology, consulting, logistics, trading, professional services, and other industries.
Another attraction is that most mainland commercial activities now permit 100% foreign ownership, subject to activity-specific restrictions. Free zones also offer foreign ownership and business establishment options suited to particular industries and operating models.
The UAE generally does not impose personal income tax on employment or personal income. However, businesses can still be subject to Corporate Tax, Value Added Tax (VAT), customs duties, and other activity-specific charges.
For Indian entrepreneurs, the UAE can provide a useful base for international expansion. The best structure depends on where your customers are located, how you plan to operate, and whether you intend to remain based in India or relocate to the UAE.
Which Business Structure Should an Indian Choose in the UAE?
The first major decision is whether to establish a mainland company, a free zone company, or a branch of an existing foreign business. Each option serves a different purpose.
1. Mainland Company Setup
A mainland company is generally suitable for entrepreneurs who want to operate across the UAE market and work with a broad range of local and international clients.
For example, an Indian entrepreneur providing IT services to UAE businesses, opening a consultancy, or establishing a trading operation may consider a mainland company, depending on the permitted activities and licensing requirements.
Most mainland activities allow 100% foreign ownership, although certain strategic or regulated activities have additional requirements. The company must obtain the appropriate licence, select a permitted legal structure, and meet any office, approval, or other requirements linked to its activity.
When should you consider a mainland company?
A mainland structure may be appropriate if you want to serve customers throughout the UAE, establish a local commercial presence, hire employees, or operate in a sector where mainland licensing is the most practical option.
The final decision should be based on your business activity rather than the assumption that every mainland company follows identical rules.
2. Free Zone Company Setup
A UAE free zone company can be suitable for entrepreneurs involved in international trading, technology, consulting, digital services, and other activities permitted by the relevant free zone authority.
Free zones offer their own licensing processes and may provide packages that combine company registration, workspace options, and eligibility for residence visas. However, available facilities and visa allocations vary by authority and package.
An Indian entrepreneur running an international consultancy or an online service business may find a free zone structure suitable, provided the selected licence covers the intended activities.
One important consideration is access to the mainland UAE market. A free zone licence does not automatically grant unrestricted permission to conduct every type of business directly in the mainland. Depending on the activity and applicable rules, a business may need additional permissions, an appropriate mainland licence, or a licensed distributor or other compliant arrangement.
Is a Free Zone Company Always Better for Tax?
No. This is a common misunderstanding.
A free zone company is not automatically exempt from UAE Corporate Tax. A Qualifying Free Zone Person may benefit from a 0% Corporate Tax rate on qualifying income if it meets the relevant conditions. Non-qualifying income may be taxed at 9%, subject to the applicable rules.
Eligibility depends on matters such as qualifying income, adequate substance in the UAE, compliance with transfer pricing requirements, and other prescribed conditions.
Therefore, choose a free zone based on your operating needs and assess any potential tax benefit separately.
3. Branch of an Existing Indian Company
If you already operate a company in India and want to expand into the UAE, establishing a branch may be worth evaluating.
A branch is an extension of its parent company rather than an entirely separate legal entity in the same way as a new subsidiary. It can be useful where an established Indian business wants to maintain continuity while developing operations in the UAE.
However, the parent company may remain directly exposed to the branch’s obligations, and the permitted activities depend on the relevant licensing rules.
A branch is not necessarily the best choice for a new entrepreneur who has no existing company. In that case, forming a new UAE company may provide a more suitable structure.
How to Set Up a Business in the UAE as an Indian
Once you have selected the appropriate structure, the next step is to follow the company formation process. The exact steps differ between mainland authorities and individual free zones, but the main stages are generally similar.
Step 1: Select Your Business Activity
Identify exactly what your company will do. Business activity determines the type of licence you need, the legal structure available, and whether additional regulatory approvals are required.
For example, a consulting company, an import-export business, and an e-commerce company may have different licensing requirements, even when all three are owned by Indian citizens.
Avoid selecting a licence only because it appears inexpensive. Confirm that it permits the activities you actually intend to conduct.
Step 2: Choose Mainland or Free Zone
Compare both options based on your customers, operating model, location, workspace needs, visa requirements, and total costs.
If you plan to serve customers throughout the UAE, a mainland licence may be appropriate. If your business focuses on international services or a permitted free zone activity, a free zone may suit your plans.
The best option is the one that supports your business model while meeting the relevant regulatory requirements.
Step 3: Reserve Your Trade Name and Select a Legal Structure
Choose a trade name that complies with the authority’s naming rules. You will also need to select the appropriate legal form, such as a limited liability company or another permitted structure.
The available legal forms and ownership arrangements depend on the licensing authority and business activity.
Step 4: Prepare Documents and Obtain Approvals
The documentation requirements vary, but Indian applicants should generally be prepared to provide identification documents, application forms, and details of the proposed business.
Where relevant, authorities or banks may request information about the parent company, ownership structure, business background, source of funds, or intended activities. Regulated businesses can require additional approvals before they begin operating.
Documents issued in India may need to meet the relevant authentication, attestation, or translation requirements.
Step 5: Complete Registration and Obtain Your Licence
After the application is approved and the required fees and formalities are completed, the authority issues the relevant company registration documents and business licence.
Check that the licence accurately reflects the business activities you plan to undertake. You should also understand the renewal requirements and maintain any office, lease, or other arrangements required for your licence.
Step 6: Open a Corporate Bank Account
Once the company has been established, you can approach a UAE bank to open a corporate bank account.
Company formation does not guarantee bank account approval. Banks conduct their own checks and may request company documents, identification and ownership details, information about customers and suppliers, expected transaction volumes, and evidence of the source of funds.
Prepare a clear explanation of your business model and the countries in which you expect to operate. This can help the bank assess the application, although the final decision remains with the bank.
Understanding UAE Corporate Tax for Indian Business Owners
UAE Corporate Tax applies to qualifying businesses according to the country’s tax rules. An owner’s Indian nationality does not, by itself, determine whether the UAE company is liable for tax.
UAE Corporate Tax Rates
Under the standard UAE Corporate Tax regime, the rates are generally:
- 0% on taxable income up to AED 375,000.
- 9% on taxable income above AED 375,000.
These rates apply to taxable income, not automatically to total sales or turnover. The taxable amount is calculated under the relevant Corporate Tax rules.
Eligible businesses may also be able to claim available reliefs if they satisfy the applicable conditions. However, relief is not automatic, and some categories of businesses are excluded from particular schemes.
Does a UAE Company Need Corporate Tax Registration?
A company incorporated in the UAE will generally need to register for Corporate Tax with the Federal Tax Authority, even when its actual tax payable may be zero.
Registration, tax payment, and return filing are separate obligations. Businesses should confirm their applicable registration deadline, maintain accounting records, and meet the relevant filing requirements.
Where applicable, the Corporate Tax return and payment are generally due within nine months after the end of the relevant tax period. The company should verify the deadlines and any exceptions that apply to its circumstances.
VAT Registration in the UAE
VAT is another important consideration when planning the finances of a new business.
The standard UAE VAT rate is 5%. For a UAE-resident business, mandatory registration generally applies when the value of its taxable supplies and imports exceeds AED 375,000 over the previous 12 months or is expected to exceed that amount in the next 30 days, subject to the applicable rules.
Voluntary registration may be available when the value of qualifying taxable supplies, imports, or taxable expenses exceeds AED 187,500 under the relevant criteria.
A business should not assume that a free zone licence removes its VAT responsibilities. Registration depends on the applicable VAT rules and the company’s activities, not merely on its location.
What Should Indians Know About Tax in India?
Setting up a company in the UAE does not automatically remove all Indian tax obligations. The position depends on the owner’s residential status, the company’s management arrangements, the source and nature of income, and the applicable Indian tax rules.
1. Your Indian Tax Residential Status Matters
Indian citizens who continue to live in India should assess their personal tax position before investing in or operating a UAE company.
Under Indian tax law, a resident and ordinarily resident individual is generally taxable in India on worldwide income, subject to the applicable provisions and reliefs. The treatment of foreign income can differ for non-residents and residents who are not ordinarily resident.
If you receive salary, dividends, business income, or other income connected with a UAE company, the relevant Indian tax treatment should be checked based on your specific circumstances.
2. Be Careful About Where the Company Is Managed
A company registered in the UAE may face Indian tax-residence questions if its key management and commercial decisions are effectively made from India.
India’s Place of Effective Management rules can be relevant to determining whether a foreign company is considered resident in India. The assessment depends on the actual facts, including where important management decisions are made.
For example, an Indian entrepreneur who incorporates a UAE company but continues to manage its entire business from India should obtain professional advice on the company’s management and tax-residence position.
Maintaining a UAE registration alone should not be treated as proof that the company has no Indian tax exposure.
3. Follow Indian Foreign Investment and Remittance Rules
If you are living in India and intend to transfer funds from India to establish or acquire a business in the UAE, you should check the applicable Foreign Exchange Management Act (FEMA) and Reserve Bank of India overseas investment requirements.
The relevant route and reporting obligations can depend on whether the investor is an individual or a company, the type of investment, and the proposed transaction. Do not assume that every business investment can be funded through the same remittance route.
Discuss the proposed investment with your authorised dealer bank and a professional familiar with Indian overseas investment rules before transferring capital.
4. Consider the India-UAE Double Taxation Agreement
India and the UAE have a Double Taxation Avoidance Agreement (DTAA). Depending on the circumstances, the agreement can help determine taxing rights and provide relief where the same income is taxable in both countries.
However, the treaty does not automatically exempt every income stream from Indian tax. Eligibility for relief and foreign tax credit depends on the relevant provisions and documentation requirements.
A cross-border tax adviser can help you assess whether relief is available and how income, dividends, or other payments should be reported.
How Much Does It Cost to Set Up a Business in the UAE?
The total cost depends on the emirate, business activity, licensing authority, legal structure, office requirements, number of visas, and other services required.
A free zone package may combine several initial services, while a mainland setup may involve separate charges for licensing, approvals, and premises. These differences mean that comparing only the advertised licence fee can give an incomplete picture.
Before selecting a package, request a breakdown covering initial registration, licence issuance, office or workspace, immigration-related charges, establishment or registration cards where applicable, visa costs, and annual renewal expenses.
You should also budget for bookkeeping, Corporate Tax compliance, VAT services when applicable, banking documentation, and any cross-border tax advice required.
How Takween Advisory Can Help Indian Entrepreneurs
Selecting the right company structure can be challenging when you are unfamiliar with UAE licensing and tax requirements. The decision becomes more complex when you also need to consider Indian investment rules and cross-border taxation.
Takween Advisory supports entrepreneurs exploring business setup in Dubai and across the UAE. Its business setup and advisory support can help applicants understand the available licensing routes, compare mainland and free zone options, and identify the setup requirements relevant to their proposed activities.
For Indian founders, company formation planning should also include a separate review of Indian tax residency, overseas investment compliance, and any potential management or reporting obligations in India. These matters may require advice from qualified tax and legal professionals in both countries.
Frequently Asked Questions
1. Can an Indian citizen own 100% of a company in the UAE?
Yes. Indian citizens can generally own 100% of an eligible mainland or free zone company. However, certain strategic or regulated activities may have additional ownership or approval requirements.
2. Is a free zone company better than a mainland company for Indians?
Not in every case. A free zone company may suit businesses focused on international activities or permitted free zone operations. A mainland company may be more suitable for businesses that need broad access to the UAE domestic market. The choice should reflect your activity, customers, and operating requirements.
3. Do Indian business owners need to pay Corporate Tax in the UAE?
A UAE company may be subject to Corporate Tax regardless of the owner’s nationality. The standard rates are generally 0% on taxable income up to AED 375,000 and 9% on taxable income above that amount. Qualifying free zone businesses may receive different treatment for qualifying income if they meet the required conditions.
4. Does a UAE company have to pay tax in India as well?
It depends on the facts. An Indian owner’s residential status, the source of income, and where the foreign company is effectively managed can affect Indian tax obligations. Professional advice is important where the owner continues to live or manage the company from India.
5. Can I establish a UAE company while living in India?
It may be possible, depending on the business activity, licensing authority, documentation, and applicable investment rules. If capital is being transferred from India, you should check the relevant FEMA and RBI requirements with your authorised dealer bank before making the investment.
6. Does a UAE company need VAT registration immediately?
Not every company needs to register immediately. A UAE-resident business generally has to register once it meets the mandatory VAT threshold or expects to meet it within the prescribed period. Special rules can apply to foreign businesses and particular transactions, so the company’s activities should be reviewed.
Conclusion
Setting up a business in the UAE as an Indian involves more than choosing a low-cost licence. You need to select the right structure, confirm the permitted activities, understand the banking and documentation requirements, and plan for UAE Corporate Tax and VAT.
It is equally important to consider your Indian tax residential status and the rules governing overseas investment and foreign-company management. A UAE company may be a valuable route to international growth, but careful planning helps you establish it on a sound legal and financial foundation.
Before proceeding, compare the mainland, free zone, and branch options against your actual business goals. Then review the UAE and Indian tax implications with the appropriate professionals so that your setup remains compliant as the company grows.