Global Propylene Oxide Market to Reach USD 36.04 Billion by 2034, Driven by Polyurethane, EV and Sustainable Production Demand
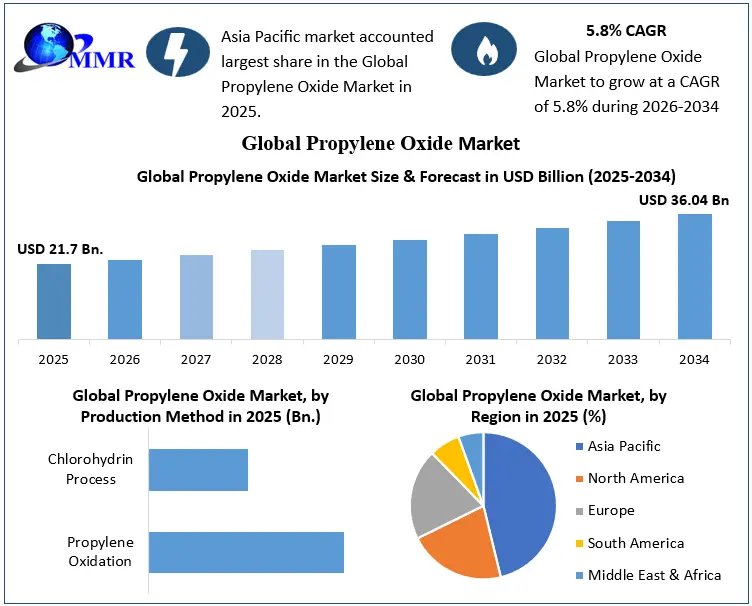
The Propylene Oxide Market was valued at USD 21.7 billion in 2025 and is projected to reach USD 36.04 billion by 2034, expanding at a CAGR of 5.8% during 2026–2034. Propylene oxide is a critical chemical intermediate used to manufacture polyether polyols, propylene glycol, glycol ethers and specialty surfactants. Increasing demand for polyurethane foams across automotive, construction, furniture, insulation and packaging is strengthening consumption, while electric vehicle production is creating new opportunities for polyurethane-based battery encapsulation, thermal management, adhesives and interior applications.
Market Estimation, Growth Drivers and Opportunities
The market outlook is supported by industrialization, urbanization and rising demand for lightweight, energy-efficient materials. Automotive manufacturers use polyurethane-derived materials for seating, insulation, vibration damping and interiors, while electric vehicles create additional demand for polyurethane-based battery thermal management and encapsulation. Construction is another major growth engine because rigid polyurethane foams support building insulation and energy efficiency.
Propylene glycol also expands opportunities in pharmaceuticals, food processing, cosmetics and personal care, while glycol ethers and specialty surfactants serve coatings, cleaning products and inks. Sustainable manufacturing is creating opportunities for hydrogen peroxide to propylene oxide (HPPO) technology. However, volatile propylene feedstock prices and higher production costs remain important challenges for producers and investors.
U.S. Market Trends and Investment
The United States remains a strategically important propylene oxide market because of its integrated petrochemical infrastructure, strong automotive and construction industries, and established polyurethane value chain. In 2025, industry activity highlighted a shift toward supply optimization and feedstock security. LyondellBasell approved an investment to expand propylene production at its Channelview Complex near Houston, with approximately 400,000 metric tons per year of additional capacity planned and startup targeted for 2028. The project is expected to strengthen propylene availability and reduce exposure to feedstock volatility, supporting downstream opportunities including propylene oxide. At the same time, Dow permanently shut down a higher-cost propylene oxide unit at Freeport, Texas, rationalizing approximately 20% of North American PO industry capacity. These developments show U.S. producers balancing capacity rationalization with targeted feedstock investment.
Request a Sample of the Full Market Report : https://www.maximizemarketresearch.com/request-sample/2515/
Market Segmentation: Largest Share
By application, Polyether Polyols hold the largest share of the global Propylene Oxide Market. Their extensive use in flexible and rigid polyurethane foams for furniture, bedding, automotive seats, construction insulation and related applications makes them the leading consumption outlet for propylene oxide. By end user, Automotive and Construction are the dominant segments, supported by continued demand for polyurethane foams, coatings, adhesives and insulation. By region, Asia Pacific held the largest market share at 46.2% in 2025, reflecting rapid industrialization, urbanization and strong manufacturing activity across China, India and Southeast Asia.
Competitive Analysis
Dow Inc. is a leading participant, supported by integrated propylene oxide and derivative operations and proprietary co-production technologies. In 2025, Dow continued optimizing its asset footprint while focusing investment on higher-value applications and efficiency improvements.
LyondellBasell Industries N.V. combines integrated production, global supply capabilities and long-term customer relationships; its 2025 Channelview propylene expansion strengthens upstream feedstock security for future downstream growth.
BASF SE is advancing sustainable chemical production through HPPO technology and operates propylene oxide joint ventures, supporting lower-impact manufacturing pathways.
Shell plc maintains a strong global position through integrated PO production and proprietary SM/PO technology, with PO derivatives serving polyurethane, coatings and other applications.
SABIC benefits from large-scale petrochemical integration and access to propylene feedstock, positioning it to serve growing derivative demand and industrial applications.
Regional Analysis
China is central to global demand because of its large polyurethane, automotive, construction, furniture and chemical manufacturing base. Government initiatives supporting fine chemicals, industrial upgrading and sustainable production favor advanced technologies and downstream investment.
Germany remains an important European chemical hub, with producers focused on energy efficiency and sustainable processes. The UK benefits from established chemical infrastructure and Shell’s downstream expertise. Japan’s advanced chemical, automotive and electronics industries support demand for high-performance intermediates. In the United States, abundant petrochemical infrastructure, propylene availability and large polyurethane-consuming industries continue to underpin the market.
Key Players
Key companies profiled in the Propylene Oxide Market include Dow Inc.; LyondellBasell Industries N.V.; Shell plc; BASF SE; SABIC; Repsol S.A.; Sumitomo Chemical Co., Ltd.; SKC Ltd.; LG Chem Ltd.; Mitsui Chemicals, Inc.; INEOS Group Holdings S.A.; AGC Inc.; Huntsman Corporation; Indorama Ventures Public Company Limited; Wanhua Chemical Group Co., Ltd.; Sinopec; PetroChina; Saudi Aramco; Evonik Industries AG; Covestro AG; and TotalEnergies SE.
Why the Propylene Oxide Market Matters Now
Propylene oxide is increasingly important as industries pursue lighter vehicles, energy-efficient buildings, advanced insulation and higher-performance polyurethane materials. Manufacturers are also under pressure to reduce emissions, manage feedstock volatility and improve efficiency. Investment in HPPO, integrated feedstock networks and capacity optimization is reshaping competition. EV growth, construction modernization, specialty chemical demand and sustainability requirements create strong long-term opportunities for producers with competitive feedstock, efficient operations and lower-impact technologies.
Explore More Related Reports:
Global L lactide Market https://www.maximizemarketresearch.com/market-report/l-lactide-market/13265/
Global Sodium Lactate Market https://www.maximizemarketresearch.com/market-report/global-sodium-lactate-market/109358/
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves industries including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through forecasts, competitive analysis and strategic consulting, MMR helps organizations understand market conditions, identify opportunities and make informed decisions.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com